How Thales is Shaping Sustainable Payment Cards
At the end of last year, Thales triumphed at the Future Digital Awards for Fintech & Payments; winning Platinum in the hotly-contested Best Modern Card Issuing Platform category.
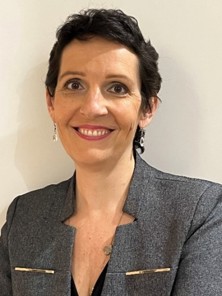 |
To commemorate this, we sat down with Sylvie Gibert, Chief Sustainability Officer, Thales DIS/BPS, to discuss the newfound importance of sustainability within financial services, the difficulties that can arise, and what the future holds for sustainable payment cards. Sylvie Gibert joined Thales in 2000 and has been Chief Sustainability Officer, Thales DIS/BPS since 2021. From 2016 to 2021, Gibert headed the Thales DIS/BPS EMV payment card business; a 1B€ business line with 28% market share worldwide. Before this, she held several positions in marketing in the Gemalto banking and payment business line, acquired in 2019 by Thales. Prior to the acquisition of Gemalto by Thales in 2019, Gibert was a board member of Gemalto SA, the French legal entity of Gemalto NV. She is also an Advisory Board Member of the Smart Payment Association; the industry body of the payments cards market. |
To what extent are sustainable payment services becoming an important consideration for banks and financial institutions?
At Thales Banking & Payment Solutions (BPS), we have more than 3500 customers worldwide who rely on us to issue payment cards and increasingly provide digital payment services for their cardholders. For that part of their business, sustainability impacts banks in two ways. First, reducing our environmental impact at all stages of all payment products or services’ lifecycles, second, ensuring a broader financial inclusion to people who cannot benefit from payment services, for disability reasons or because they are unbanked.
Payment services are highly regulated and in recent years, directives about accessibility profoundly changed the way we innovate at Thales: every new product or service has to be more sustainable by design, user-centric and inclusive. Also, the payment card market is committed to replace the use of plastic by eco-friendly material by 2030. Major payment networks have issued mandates in that direction to all card issuers using their payment schemes. The journey has started, and Thales leads the way.
In fact, rather than constraints, these regulations and mandates are proving to be great business opportunities for banks. Innovative card bodies are great marketing and branding tools for card issuers; enabling better cardholder segmentation and answering clear consumers’ demand for responsible payment services. Such cards increase customer engagement and reinforce their relationship with the bank.
Financial inclusion is all about empowering more people to benefit from secure and intuitive payment services. For example, Thales has developed a voice card for visually impaired people who can now be sure of the amount paid at the point-of-sale terminal, as it is voiced by their connected smartphone. This one inclusivity win is calling for many more: solutions that solve disability pain points in the payment journey. Not only this is deeply positive and inclusive impact-wise, but it also translates into an increase in customer acquisition and potentially more transactions for the bank. Sustainability is hence not only a duty, but also an opportunity.
How is Thales addressing the need for sustainable payment cards?
As the world leader for payment card issuance, Thales leads the way for a more sustainable future of the payment card industry. We have a four-pillar strategy to tackle this immense objective:
- We act for Climate: By reducing CO² emission reduction at all stages of the card lifecycle, from ordering, manufacturing, personalisation, transport, and end-of-life recycling. We also look at digital services and their CO² impact. To do so, we have built a tool to allow our customers to assess their current CO² emissions and identify areas to reduce them.
- We act for Nature: By replacing PVC with more eco-friendly, PVC-free card bodies.
- We act for People: By designing inclusive innovative payment services, for people with disabilities and those who cannot seamlessly benefit from today’s solutions.
- We act for Engagement: By triggering changes in people’s behaviour; leveraging the mobile channel to deliver user-centric, user-in-control payment experiences which are responsible and inclusive.
What difficulties come with changing to a sustainable payment cards model, and how is Thales solving these?
Sustainable payment services come with a cost to the bank. However, the brand-image benefits and the capacity to better segment cardholders and provide new inclusive services largely offset the cost impact of being sustainable. The cost of no-action is, conversely, unbearable for banks as consumers’ demands for responsible, and inclusive products and services is now equally important to demands for security and convenience. Sustainability is a two-way engagement between a bank and its cardholders who are concerned, aware and want to make an active contribution towards a positive impact.
For Thales, sustainability is an increased R&D effort and cost, but the reward largely offsets the effort. We scrutinised all steps of the card journey to improve the sustainability impact: from card body material, circularity ie putting in place collection and recycling solutions and developing local solutions for production and personalisation, cutting down on transport impacts, and using for example sea freight rather than airplanes whenever possible. We also maximise the use of digital to improve the way cardholders order their card, receive their PIN code digitally, and personalise their payment experiences. Digital is also improving card issuers’ operations by optimising data and product flows.
Education is key. Sustainability wins can now come at the expense of lead time. At Thales, we do believe the market is ready for such profound changes but sometimes, education and time are still needed to support them.
What benefits do banks and financial institutions get from having a strong sustainability strategy?
There are clear customer engagement and brand image benefits for banks. Cardholder expectations leave no room for delays in action. The payment industry is very dynamic with new, agile fintech disruptors which are sustainable-native, digital-native, and extremely agile innovation-wise.
Additionally, the environmental impact and the regulations at stake are now mission critical for banks. It’s not wishful thinking; it’s a business mandate. In fact, the real question to ask in 2024 is rather: what would be the penalty for bank and financial institutions to not have a strong sustainability strategy in place?
Are there any sustainable card deployments you're particularly proud of?
Yes. We have many achievements for which we are very proud:
- Wood cards: A true “zero plastic” product empowering banks that meets the demand for a high-end, highly engaged user segment.
- Cards made using ocean plastic waste.
- The voice payment card for visually impaired people, in which the card is Bluetooth-connected to the cardholder smartphone to voice the amount at the point-of-sale terminal. La Banque Postale in France recently communicated about its experimentation of this great, beautiful, and inclusive use case.
What do you see as the future of sustainable payment cards?
- An increasingly digital journey; empowering cardholders to order, setup then use their very own card portfolio. For example, allowing the cardholder to choose whether they need a physical card or not, and if not, get an in-app virtual card instead.
- A 100% PVC-free card base. Zero virgin nor recycled PVC, but rather more eco-friendly or bio-sourced material.
- An unboxing experience with sustainable packaging.
- PIN definition via mobile, meaning no more PIN paper mailer).
- Full control of the end user throughout the entire end user journey.
- Recycling of end of life cards.
Related Research
-
 ReportNovember 2025Modern Card Issuing
 Jawad JahanModern Card Issuing Platforms Market, 2025-2030
Our Modern Card Issuing Platforms Market research suite provides a detailed and insightful analysis of this evolving market; enabling stakeholders from banks, financial institutions, fintech companies, and technology vendors to understand future growth, key trends, and the competitive environment.
VIEW -
 ReportNovember 2024Fintech & Payments
 Daniel BedfordFuture Leaders 100, Fintech 2025
Our Future Leaders 100: Fintech 2025 research suite is dedicated to identifying the most innovative start-ups within fintech which have the disruptive potential to reshape the fintech landscape.
VIEW
Latest research, whitepapers & press releases
-
 ReportOctober 2026Fintech & Payments
 Michael GreenwoodAccounts Payable Automation Market: 2026-2031
Our Accounts Payable (AP) Automation research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders to understand future growth, key trends and the competitive environment.
VIEW -
 ReportOctober 2026Fintech & Payments
 Jawad JahanCrypto-gaming Market: 2026-2035
Our Crypto-gaming Market research suite provides an insightful analysis of this rapidly growing market; enabling stakeholders - from crypto-gaming and sportsbooks operators, prediction market platforms, business-to-business (B2B) gambling platforms and software providers, to crypto payment processors and regulators - to understand future growth, key trends, and the competitive environment.
VIEW -
 ReportOctober 2026Telecoms & Connectivity
 Alex WebbRetail Roaming Market: 2026-2031
Our Retail Roaming research suite for mobile network operators (MNOs) and mobile virtual network operators (MVNOs) provides detailed analysis and strategic recommendations for the next era of retail roaming.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Dr Manju ChhillarEmbedded Finance Market: 2026-2031
Embedded finance is one of the fastest-growing markets in financial services, and is about to accelerate even further. Our Embedded Finance Market research provides detailed analysis of the key drivers behind this growth, and what these mean for stakeholders in this market.
VIEW -
 ReportSeptember 2026Identity & Security
 Thomas WilsonApplication Security Market: 2026-2031
Our Application Security research suite provides detailed analysis of this emerging market; allowing application security providers to gain an understanding of key security trends and challenges, potential growth opportunities, and the competitive environment.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Shane O'SullivanBanking Fraud Prevention Market: 2026-2031
Our Banking Fraud Prevention research suite provides a comprehensive and in-depth analysis of the types of fraud currently impacting the banking sector, and the evolving methods that can be used to overcome them.
VIEW


-
 WhitepaperOctober 2026Fintech & Payments
Michael Greenwood
Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs
Our complimentary whitepaper, Accounts Payable Automation ~ How Businesses Are Reducing Operational Costs, analyses how AP automation is combatting costs by decreasing the need for manual processes, and provides strategic insight into a number of key trends in the AP automation space.
VIEW -
 WhitepaperOctober 2026Fintech & Payments
Jawad Jahan
Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma
Our complimentary whitepaper, Compliance or Anonymity - The Crypto-gaming Operator’s Dilemma, analyses the current regulatory landscape of the crypto-gaming market.
VIEW -
 WhitepaperOctober 2026Telecoms & Connectivity
Alex Webb
Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt
Our complimentary whitepaper, Reimagining the Future of Retail Roaming – How Mobile Network Operators Must Adapt, explores the emerging opportunities for MNOs within retail roaming.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Dr Manju Chhillar
Emerging Markets: The Next Opportunity for Embedded Finance
This free whitepaper examines how a combination of multiple factors is driving North America towards saturation for embedded finance.
VIEW -
 WhitepaperSeptember 2026Emerging Technology
Thomas Wilson
Vibe Coding: The Fastest-growing Threat to Application Security Today
Our complimentary whitepaper, Vibe Coding: The Fastest-growing Threat to Application Security Today, examines the state of the application security market; considering its impact on different verticals, and how it is being employed in these verticals to best combat malicious attackers and keep sensitive data safe.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Shane O'Sullivan
The Fraud Frontier: Securing Banking in an AI-driven Era
Our complimentary whitepaper, The Fraud Frontier: Securing Banking in an AI-driven Era, examines the rapidly evolving state of the banking fraud prevention market.
VIEW


-
Fintech & Payments
Accounts Payable Automation to Save Global Businesses 6.2 Billion Hours by 2031, Accelerated by Business System Integration
October 2026 -
Fintech & Payments
The 25th NextGen Payments & RegTech Forum Arrives in Athens, Greece
October 2026 -
Fintech & Payments
Crypto Gaming: Wagers to Reach $1.3 Trillion by 2035, as Crypto Rails Widen Global Access Despite Regulatory Challenges
October 2026 -
Fintech & Payments
Juniper Research Unveils Identity & Security Award Winners for 2026
October 2026 -
Retail Roaming Revenue to Fall $4 Billion By 2031, as Regulatory Restrictions and Competition Bite
October 2026 -
Fintech & Payments
Soft POS to Surpass 100 Million Installations in 2030
September 2026