eCommerce Fraud Prevention - An Interview with Visa
Visa was recently identified as the leading vendor in our eCommerce Fraud Prevention Market 2025-2030; based on the strength of its global network, the quality of its AI-driven fraud decisioning, and the powerful impact of its investments, such as the acquisition of Featurespace in 2024.
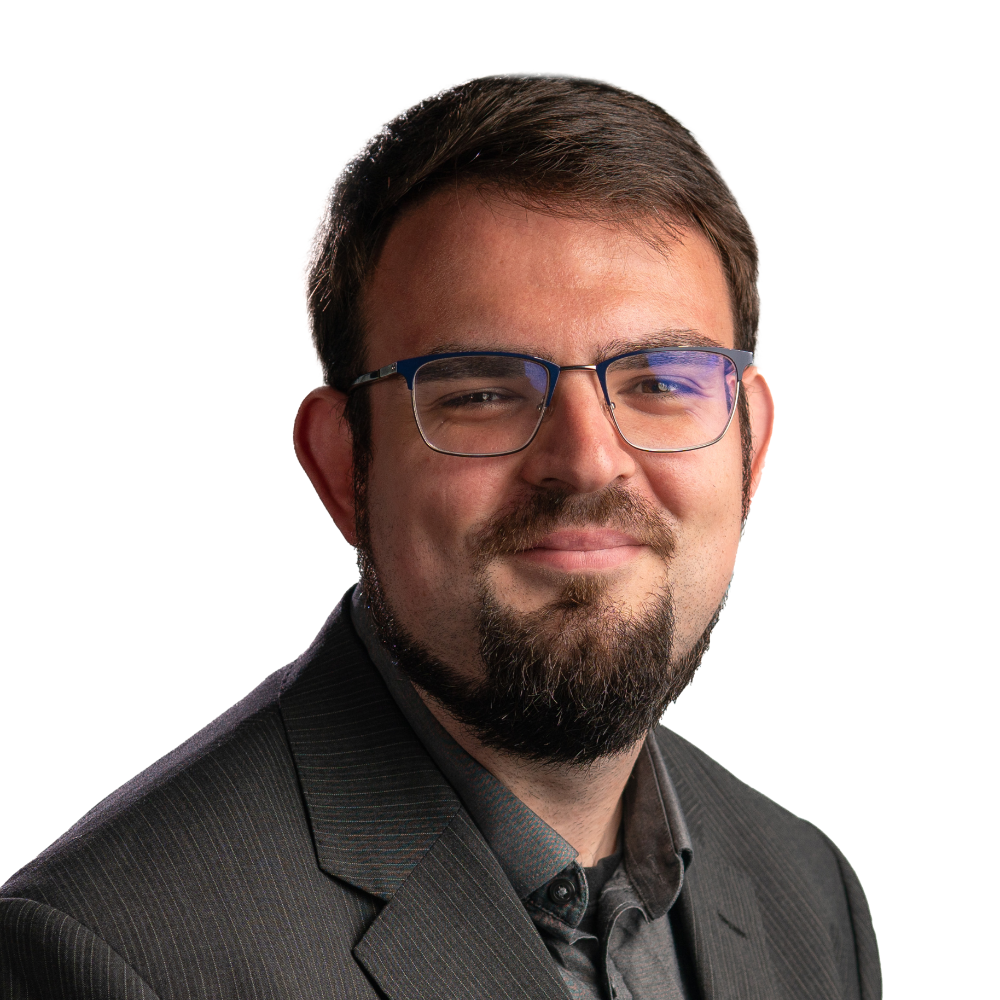
To find out more about its market-beating proposition, Nick Maynard, our VP of Research, sat down with Eric Goodman, VP of Acceptance Risk and Authentication Solutions at Visa, to discuss how eCommerce fraud is evolving, the solutions being developed to fight back, and why Visa is leading the market.
You can also read the full transcript below.
Nick: So, thanks for joining me today. I am joined by Eric Goodman, VP of Acceptance Risk and Authentication Solutions at Visa. So, welcome Eric.
Eric: Great to meet you, thanks for having me.
Nick: Firstly, what I need to say is congratulations to Visa on being ranked number 1 in our eCommerce Fraud Prevention report in our Competitor Leaderboard. So, congratulations for that to start with.
Eric: Thank you, we appreciate that. The engagement in the process is really reassuring, in that we believe we are doing the right things to deliver value, risk protection, and revenue protection to our customer base.
Nick: With that in mind, let's jump into a few questions about what Visa are seeing in the market.
Firstly, what key trends and challenges are you seeing within eCommerce fraud prevention today, and how are things changing over time?
Eric: Sure, yeah so, fraud prevention has moved from what I would traditionally say is single point in time - I have a transaction, I’m going to inspect that transaction, make a predictive risk identification about that transaction, and then either give our merchant or acquirer the ability to make a decision and move onto authorisation.
Prevention can start way sooner than the actual point of transaction. And it can also be reviewed or analysed post transaction; what we call post purchase. So, you’re certain to merchant demand, and acquirer demand, for solutions that stretch across the entire transaction lifecycle. Examples are account login, and what are we doing around secure merchant accounts and wallet accounts. As consumers, we log in and store credentials and our payment information, then we move into transaction monitoring, which could be authentication, predictive fraud intelligence, velocity, a lot more use of behavioural intelligence, or does Eric’s behaviour look normal, based on his pattern of shopping. At the time of dispute - return of refunding query - does Eric’s behaviour look normal and common?
And all of that is geared towards maximising throughput revenue for merchants at any point of time. As we discussed earlier, I can maximise revenue by letting every single transaction go through. I’m probably also going to maximise fraud at that point. You’re finding out where can I detect risk signals, and where can I power that customer journey to maximise acceptance rate while managing and keeping fraud low or at a manageable level; meeting business goals.
Nick: Makes sense, and that’s what we’ve been seeing in the market as well. Fraud prevention is becoming increasingly predictive. It is using a lot of different metrics, a lot of different methods. It is becoming a real coming together of how the market is actually approaching this. The approach has gone from being quite simplistic – is it approval, is it rejection - to this whole ecosystem of predictive tools, behavioural analytics and network signals. All these different elements are creating this ecosystem where there are lots of different tools that can have an impact here.
Eric: Yeah, and in our merchant ecosystem that exists, a merchant itself could be a point of fraud attack, where we think traditionally, my card is compromised, my card is being used to commit transactional fraud. Now, with merchant behaviour, say me and you run small business, and maybe this is not our expertise, and someone is trying to overtake our merchant storefront, and then they can use that for all sorts of nefarious things they may want to achieve. That’s where monitoring signals are starting to change; where we provide tools and insights to different parts of the ecosystem, so they have better visibility.
There are larger-enterprise merchants who are probably doing the same thing - expanding the payment options I want to accept - and those options may be different ways for how authorisation and settlement occur. So, being able to have a fraud platform that is flexible, that is being on payment method, utilisation, location in the world, all those things start to matter in and end-to-end strategy.
Nick: Makes complete sense.
Touching on how the role and tools used within eCommerce fraud prevention are changing, how big a role do you see for network-level intelligence within fraud prevention.
Eric: At Visa, and as a product manager at Visa, I have a big advantage; where I have the largest payments network, that has hundreds of billions of datapoints for our AI/ML models and predictive intelligence to assess and leverage. I can use that intelligence and serve it as part of a point solution for any one of those cases that I just described. Where I can also deploy machine learning or predictive fraud intelligence at the specific use case or merchant interaction. Those things put together are really powerful.
At Visa, specifically with our Featurespace platform, we can now pull in behavioural analytics. I can pull in behavioural risk intelligence as well. So, we’re starting to see this layered signal approach, that we can serve as risk signals that merchants can consume within their own decision methods, or leverage our own risk platforms and tools and write risk strategies on top of our platforms. That’s where our network-level intelligence is really powerful.
What also can happen though, is that once it leaves my platform capabilities, I have insight and signal about that transaction, and I'd like to be able to share that into the network to reach the issuer. Visa has a strong data share capability, where from 3DS authentication, data-only authentication, and other risk signal and tools, we can inject intelligence into the authorisation for issuers. We can do that multi network as well.
You can do that with Discover and other payment networks, Mastercard, and other networks, that enables issuers around the world to receive additional intelligence. And that kind of ecosystem lifecycle becomes really powerful in terms of optimising revenue for both merchant acquirers and issuers; meaning we’re improving the good transactions, doing a good job of finding the bad transactions, and keeping fraud out of the ecosystem the best we can.
Nick: Makes complete sense, and I think probably the answer to that question helps to answer the next one as well. As I mentioned, Visa was ranked first in our eCommerce Fraud Prevention Competitor Leaderboard.
For you, what makes Visa stand out in this space? What’s that real USP that is helping you achieve what you need to here?
Eric: Thank you for the recognition. Our Visa Protect platform, or suite of capabilities, as we discussed earlier, is now enabling us to end to end the lifecycle of a consumer’s transaction, and inject predictive fraud intelligence at each step of that transaction. That’s a really powerful platform-level solution that a merchant, merchant acquirer/processor is looking for today. In today’s fraud landscape, we have capabilities at the point of entry into a merchant website, at account log in, at point of transaction, then everything post transaction - dispute, refund, return. Those signals under one unified platform is a really powerful way to give a fraud analyst, a fraud manager, a fraud strategist the ability to look across the lifecycle of the transactions they are accepting, and make better decisions on what to accept, what to inspect, and what to reject.
That combination of tools is really powerful. That showed up in the report, and really helped us with our ranking. And what we just talked about, to your point, is we then have the network level. We have the hundreds of billions of transactions that Visa processes every year; giving us a whole other set of inputs and signals to power each of those decision points from a signal perspective. And bringing those together is a really big advantage. So, as a product owner, I love it. I can design a solution based on our customer feedback, on our customer need, but I have this larger set of transactional data, and a fantastic predictive fraud intelligence team, that helps us write new model capabilities. We talked about bringing behavioural intelligence into our model and capabilities, and that’s been Visa’s sweet spot for decades.
AI/ML predictive fraud intelligence has been the heart of the Visa platform for a very long time. We’ve now been extending those capabilities into both sides of the ecosystem - the acceptance side, the issuance side - really, really powerful when you put those things together.
Nick: That was our sense when we were doing the ranking, as well. That, actually, Visa could have sat back and enjoyed the use of its tools - like you say, the AI & ML excellence you guys have demonstrated - over many years. You’ve definitely not done that. You’ve acquired businesses, you’ve rolled out new capabilities, you’ve created large-scale data tools, and actually, I think the combination of those, it's not even just cards anymore, Visa A2A protect is a really interesting capability as well. I think across the piece, there’s just such strength in what Visa is doing in this space.
Eric: Two important things you just touched on. One, is going beyond cards, account-to-account, there’s emerging payment technologies, stablecoin, wallet platform providers all over the world, where Visa powers a lot of that payment processing and risk intelligence into those solutions. So, that’s powerful.
And then strategic investments, acquisitions. We have quite a bit of capability to build tools and solutions that our customers need, but there is also lots of innovative work around the globe that we have this advantage to keep an eye with, invest with, maybe make a strategic acquisition to balance out our solutions and capabilities. And you’ve seen that happen over the last decade. That’s happened time and again. I’m at Visa through one of those acquisitions, right, so that’s a really powerful way for us to continue to strengthen our portfolio of capabilities, innovate, modernise our capabilities. It's an important part of how we assess the fraud landscape.
Nick: Brilliant. We could talk about fraud and how Visa is approaching it all day long, but I think we’ve covered some really great points there. So, thanks very much for speaking with us today about how Visa is approaching this really interesting market, and I’m sure we’ll be speaking again soon.
Eric: Great, thanks Nick, appreciate it.
Download the full report discussing Visa's recognition in our latest eCommerce Fraud Prevention Market 2025-2030, including the complete ranking of the top 20 competitors; along with an in-depth presentation of Visa's fraud prevention capabilities.
Find out more about Visa's AI-drive fraud management services here: https://www.visaacceptance.com/en-us/solutions/ai-driven-fraud-management.html
Related Research
-
 ReportDecember 2025Fintech & Payments
 Shane O'SullivaneCommerce Fraud Prevention Market, 2025-2030
Our eCommerce Fraud Prevention research suite provides a detailed and insightful analysis of this evolving market; enabling stakeholders from financial institutions, law enforcement agencies, regulatory bodies and technology vendors to understand future growth, key trends, and the competitive environment.
VIEW
Latest research, whitepapers & press releases
-
 ReportSeptember 2026Fintech & Payments
 Dr Manju ChhillarEmbedded Finance Market: 2026-2031
Embedded finance is one of the fastest-growing markets in financial services, and is about to accelerate even further. Our Embedded Finance Market research provides detailed analysis of the key drivers behind this growth, and what these mean for stakeholders in this market.
VIEW -
 ReportSeptember 2026IoT & Emerging Technology
 Thomas WilsonApplication Security Market: 2026-2031
Our Application Security research suite provides detailed analysis of this emerging market; allowing application security providers to gain an understanding of key security trends and challenges, potential growth opportunities, and the competitive environment.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Shane O'SullivanBanking Fraud Prevention Market: 2026-2031
Our Banking Fraud Prevention research suite provides a comprehensive and in-depth analysis of the types of fraud currently impacting the banking sector, and the evolving methods that can be used to overcome them.
VIEW -
 ReportSeptember 2026Telecoms & Connectivity
 Nick MaynardPrivate LTE & 5G Networks Market: 2026-2031
Our Private LTE & 5G Networks research suite provides detailed and insightful analysis of this evolving market; enabling stakeholders - from private LTE & 5G network platform specialists, mobile network operators, and diversified technology companies - to understand future growth, key trends, and the competitive environment.
VIEW -
 ReportSeptember 2026Fintech & Payments
 Michael GreenwoodOmnichannel Payment Platform Market: 2026-2031
Our Omnichannel Payment Platform research provides detailed analysis of this rapidly emerging market; allowing omnichannel payment platform providers to gain an understanding of key payment trends and challenges, potential growth opportunities, and the competitive environment.
VIEW -
 ReportSeptember 2026IoT & Emerging Technology
Nick MaynardIdentity & Access Management Market: 2026-2031
Our Identity & Access Management research suite provides detailed and insightful analysis of this evolving market; enabling stakeholders - from Identity & Access Management platform specialists, cybersecurity vendors, and diversified technology companies - to understand future growth, key trends, and the competitive environment.
VIEW


-
 WhitepaperSeptember 2026Fintech & Payments
Dr Manju Chhillar
Emerging Markets: The Next Opportunity for Embedded Finance
This free whitepaper examines how a combination of multiple factors is driving North America towards saturation for embedded finance.
VIEW -
 WhitepaperSeptember 2026IoT & Emerging Technology
Thomas Wilson
Vibe Coding: The Fastest-growing Threat to Application Security Today
Our complimentary whitepaper, Vibe Coding: The Fastest-growing Threat to Application Security Today, examines the state of the application security market; considering its impact on different verticals, and how it is being employed in these verticals to best combat malicious attackers and keep sensitive data safe.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Shane O'Sullivan
The Fraud Frontier: Securing Banking in an AI-driven Era
Our complimentary whitepaper, The Fraud Frontier: Securing Banking in an AI-driven Era, examines the rapidly evolving state of the banking fraud prevention market.
VIEW -
 WhitepaperSeptember 2026Telecoms & Connectivity
Nick Maynard
How Private Cellular Networks Are Unlocking Industry 4.0
Our complimentary whitepaper, How Private Cellular Networks Are Unlocking Industry 4.0, examines how private LTE & 5G networks are reshaping the way industry works.
VIEW -
 WhitepaperSeptember 2026Fintech & Payments
Michael Greenwood
How Omnichannel Payment Platforms Are Streamlining Merchant Operations
Our complimentary whitepaper, How Omnichannel Payment Platforms Are Streamlining Merchant Operations, examines how merchants are utilising omnichannel payment platforms to capitalise on customer data and integration with other business management software in order to minimise inefficiency.
VIEW -
 WhitepaperSeptember 2026Telecoms & Connectivity
 Jawad Jahan
Beyond the Headlines: What the 'AI Bubble' Really Means
Our complimentary whitepaper, Beyond the Headlines – What the 'AI Bubble' Really Means, analyses the scale and structure of AI infrastructure investment in the West, and the channels through which it could transmit stress to the wider financial system.
VIEW


-
Fintech & Payments
The Global Trade Finance Expo Arrives in Dubai, UAE
September 2026 -
Fintech & Payments
The Vision Forex Forum Arrives in Dubai, UAE
September 2026 -
Fintech & Payments
Embedded Finance Revenue to Reach $617 Billion Globally by 2031, as B2B Revenue Surges 390%
September 2026 -
IoT & Emerging Technology
AppSec Enterprise Spend to Approach $13 Billion Globally by 2031, as Market Leaders Revealed in New Competitor Leaderboard
September 2026 -
Fintech & Payments
Banking Fraud to Reach 2.2 billion Transactions by 2031, Fuelled by Growing AI-enabled Attacks
September 2026 -
Telecoms & Connectivity
Private Network Spend to Exceed $84 Billion Globally by 2031, as Market Leaders Set to Capitalise
September 2026